MORTGAGE LENDING GROUP LLC · SEATTLE & BEYOND
A mortgage that
fits your life.
More choices. Clear answers. A team that follows through.
Your first home, your next move, or a fresh look at your mortgage. Start with what matters to you. We’ll help you compare the ways to get there.
Explore what’s possibleHear from our clientsServing Seattle from our Edmonds office.
English & Spanish · NMLS #1157983 · CL-1157983
MORE OPTIONS. EXPERIENCED GUIDANCE. REAL FOLLOW-THROUGH.
200+
Wholesale lenders
Available through our lending partnership, giving you more options to compare.
$40M+
Closed in 2026
Experience moving mortgage plans through to closing.
20+ years
Of mortgage experience
Enrique has worked in mortgages since 2005, helping clients understand the full picture.
Lender access and year-to-date closing volume as of . Loan options depend on your circumstances and lender requirements.
Professional education behind your guidance. Enrique’s AMP designation is awarded by the Mortgage Bankers Association. View the credential
01 / YOUR STARTING POINT
What would you like to make possible?
A home, more flexibility, or simply a clearer plan. Explore your starting point.
Picture the home. Get comfortable with the numbers.
A first home or your next home starts with a payment that leaves room for the life around it.
- 01
Find a comfortable payment
Start with your everyday budget and the cash you want to keep.
- 02
Compare financing options
See how down payment, fees and loan choices work together.
- 03
Prepare for the purchase
Know the documents, property questions and next steps.
A CLEAR PATH. CONTINUED SUPPORT.
For your next move.
And the life after it.
Understand the decisions ahead and the support you can plan on along the way.
Before you commit
Discuss your goals
A comfortable payment, cash on hand, your timeline. We start with what matters to you.
Consider the options
Compare financing choices side by side, including keeping your current mortgage when that fits best.
Check costs & break-even
Look at fees, points and total costs over your timeline—not just the monthly payment.
Explore break-evenWhat to know
For a refinance or paid discount points, compare the upfront cost with the expected benefit and how long you plan to keep the loan.
From your decision to your first payment
Choose when to lock
Review pricing, lock length and extension costs against your closing date and comfort with rate changes.
What to know
A lock protects specified terms for a limited time, subject to its conditions. Timing cannot guarantee the lowest available rate.
Close with a clear picture
Review the final numbers and remaining steps together. Know what is due, when and to whom.
Follow up on payment one
Check your first due date, servicer details and payment setup so you know what happens after closing.
As your life and goals change
Build a savings routine
Explore autopay and optional extra-principal payments that fit your budget and could reduce interest.
What to know
Autopay alone does not reduce interest. Set it up with your servicer; confirm how extra payments reach principal, any fees or prepayment terms, and that the amount leaves room for your other priorities.
Revisit about every six months
Agree on a check-in to revisit your goals, current loan and available options—or reach out sooner when life changes.
What to know
A lower advertised rate is a starting point for a comparison. Include closing costs, the new loan term and break-even before deciding whether a change is worthwhile.
Your priorities lead.
We help you make the next decision.
REAL PEOPLE. YOUR PRIORITIES.
You bring the goal.
We help with the next step.
You deserve clear explanations, thoughtful comparisons and someone you can reach. Meet your loan officer and start where you feel comfortable.
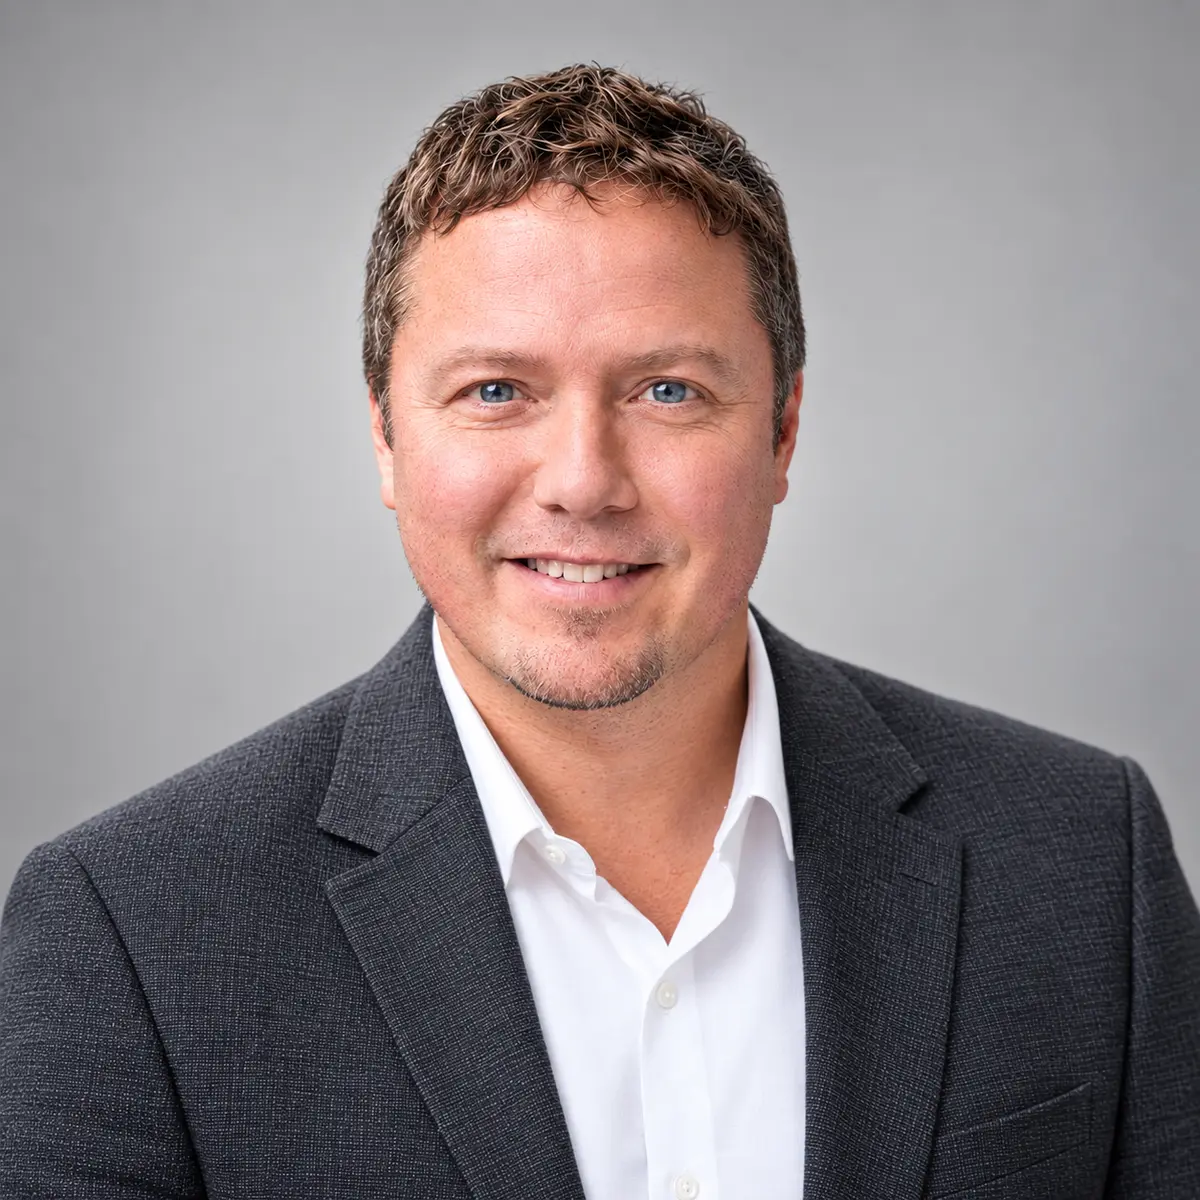
Talk with a real loan officer. Book requests are confirmed personally; written answers and calculators are here whenever you want to explore.
Send Enrique your next-step request
Just researching? Browse written mortgage answers. These educational resources are separate from a personal conversation with Enrique.
The details, at your pace.
Explore the tools, local guidance and answers behind your next decision.
Seattle homes, neighborhoods and loan limits

A PLAN FOR THE HOME YOU HAVE IN MIND
Buying in Seattle?
Start with the full picture.
Compare a condo’s association costs, the cash needed for a larger loan, or a first-home budget. See how property details and loan terms affect your budget.
Have a property in mind? Talk through the details with Enrique →
Compare a Loan Estimate
LOAN ESTIMATE REVIEW
Compare your
Loan Estimate.
You deserve to understand what you’re paying for. Share your Loan Estimate to compare the rate, upfront costs, and monthly payment—and see whether another option could fit your plans better.
Review my Loan EstimateNo obligation. No credit pull for this review. Savings aren’t guaranteed.
Have a question first? Ask Enrique →
- Share your Loan EstimateUpload the PDF you received from your lender.
- Tell us what matters mostA comfortable payment, less cash upfront, or the overall fit.
- Get a personal reviewYour loan officer will walk you through the costs and tradeoffs so you can decide with confidence.
Calculate a payment, refinance or equity option
YOUR MORTGAGE TOOLKIT
Compare mortgage payments,
costs and tradeoffs.
Explore a monthly payment, a refinance, or a way to consolidate debt. Start with your numbers. See the tradeoffs.
01 / HOME PAYMENT
What could your monthly payment look like?
Adjust the example amounts to fit the home you have in mind.
Taxes, insurance & other costs
No credit check. No contact details needed to calculate.
ESTIMATED MONTHLY PAYMENT
$3,857/month
$520,000 loan · 30-year term
- Principal & interest
- $3,287
- Property taxes
- $450
- Homeowners insurance
- $120
- Mortgage insurance + HOA
- $0
Illustration only, not a lender quote or APR. Your rate is an editable assumption. Add any applicable mortgage insurance and HOA costs above. Closing costs are excluded.
02 / REFINANCE SAVINGS
See what a lower rate could change.
What if your rate were 0.5 or 1 percentage point lower? Both options keep your remaining payoff period unchanged. Replace the example values with your mortgage details.
Keep your current mortgage$2,827/mo principal & interest$448,135 remaining interest$848,135 remaining payments
6.500% illustrative rate
$2,701/mo P&I
- Monthly payment savings
- $126
- Remaining loan interest
- $410,249
- Total payments + upfront costs
- $815,249
- Net lifetime savings
- $32,886
- Closing-cost break-even
- 40 months
6.000% illustrative rate
$2,577/mo P&I
- Monthly payment savings
- $250
- Remaining loan interest
- $373,162
- Total payments + upfront costs
- $778,162
- Net lifetime savings
- $69,973
- Closing-cost break-even
- 21 months
Lifetime means the remaining 300 months from today. Net savings subtract upfront closing costs; costs are not financed. Assumes fixed rates, fully amortizing loans, monthly payments, no extra payments or prepayment penalties. Taxes, insurance, mortgage insurance and HOA are excluded. Actual available terms may differ. Break-even compares upfront costs with monthly P&I savings.
Review my comparison with Enrique →Your calculator summary stays in this tab until you choose to include it in your private conversation.
03 / DEBT CONSOLIDATION
Keep your mortgage. Explore your equity.
Keep your existing mortgage and compare payments on debts you would pay off with a home equity line. Enter balances and current monthly payments; do not include your first mortgage.
$35,000 initial HELOC draw$1,050/mo current debt payments
$233/month
- Monthly payment reduction
- $817
During an interest-only draw period, this payment does not reduce your balance.
$293/month
- Monthly payment reduction
- $757
Principal and interest, assuming this balance is amortized at the same rate with no further draws.
8% is an editable example, not an offered rate. HELOC rates usually vary and payments may rise. Fees are excluded. Lower payments do not establish lifetime interest savings; extending repayment can cost more. Your home secures the line and could be lost if you cannot repay. Eligibility, available equity and lender terms require review. Read the CFPB HELOC guide ↗
Review my comparison with Enrique →Your calculator summary stays in this tab until you choose to include it in your private conversation.
Illustrations to help you plan. Actual loan terms require a personal review.Explore cash-out refinancing
Mortgage guides, checklists and learning resources
A MORE INFORMED NEXT STEP
Mortgage guides.
Answers you can use.
01 · PLAN YOUR PURCHASECash-to-close planner
Know what to bring and what could remain in savings.
02 · COMPARE YOUR OPTIONSCompare your Loan EstimateSend your Loan Estimate for Enrique’s personal review.
03 · GET READY TO CLOSEYour buying roadmapA personalized checklist, in English or Spanish.
04 · PLAN YOUR NEXT MOVEMortgage WatchReview your current loan and watch for offers that fit your goals.
Buying your first home in Washington · Compare a mortgage broker and lender · HELOC or cash-out refinance?
Explore Washington Home Advantage assistance · Understand DSCR financing for rental properties
What should I know before choosing a mortgage?
Broker or bank: which should I choose?
A broker helps you compare participating lenders; a direct lender makes the loan. Neither is always cheaper. Compare written offers using the same loan amount, term and lock period, including points, fees and credits.
Compare roles, fees and questions to ask →What cash do I need besides a down payment?
Budget for loan and settlement charges, prepaid items and any initial escrow deposit. Deposits and applicable credits affect cash to close. Keep a separate cushion for moving, repairs and emergencies.
Build a cash-to-close plan →Where do I start with Washington assistance?
Start with Washington State Housing Finance Commission resources and ask a participating lender for current written terms. Compare eligibility, education, repayment and the complete financing package; assistance is not automatically free money.
Questions to ask about assistance →Should I buy now and refinance later?
Make sure today’s payment works without a future refinance. Rates, home values and your eligibility can change, and refinancing has costs. Compare buying and waiting with several assumptions, including an unfavorable outcome.
Prepared with AI assistance for Enrique Pelayo Jr, AMP · Updated September 20, 2026. Educational planning, not an approval or rate quote. Read the open pre-approval checklist.
FIRST-TIME HOMEBUYERS · KING COUNTYYour first home starts
Your first home starts
with a clearer plan.
Explore down-payment options and the costs to plan for beyond your down payment.
Read the guideHELP WITH YOUR NEXT DECISION
Homebuying decisions · 6 min read10 questions to ask a mortgage broker before you apply
Homebuying decisions · 6 min readBest Seattle suburbs for homebuyers: a shortlist by buyer priorities
Homebuying decisions · 6 min readBuying a condo in Seattle: what should you ask about financing and HOA costs?
Homebuying decisions · 6 min readCan I discuss Washington mortgage options using an ITIN?
First home · 7 min readFirst-time home buyer in Washington: from budget to closing
First home · 7 min readWho qualifies for WSHFC Home Advantage in Washington?
Looking for details close to home? Start with Edmonds, Everett, or explore our published Washington city guides with local planning questions and budget tools.
Already have a Loan Estimate? Let’s review the costs together
More ways to explore your mortgage options
START WHERE YOU ARE
A home loan for
your next chapter.
You might have a specific goal or just a few questions. Choose what’s on your mind, and we’ll work through the details together.
More client experiences and review sources
CLIENT EXPERIENCES · ENRIQUE PELAYO JR
Clear explanations. A person who follows through.
Google4.9 / 543 reviews · View source ↗Zillow5.0 / 515 reviews · View source ↗
Ratings shown separately, checked . Visit each source for current ratings and all reviews.
Google · Review excerpt
“incredibly transparent from the start.”
Google · Review excerpt
“professional, knowledgeable, and always available whenever we had questions.”
Zillow · Review excerpt
“very responsive”
Selected excerpts about Enrique’s work, checked September 26, 2026. Experiences reflect their original dates and may predate the current company affiliation. Individual results vary.
Explore your homeowner report
FOR THE HOME YOU ALREADY OWN
Your home.
A fresh perspective.
See your mortgage and estimated equity together. Explore what a refinance, extra payments, or your next home could look like—with your loan officer a click away.
Search common mortgage questions
START WITH A CLEAR ANSWER
Do you really need 20% down?
Eligible buyers may have options with less. See the official guidance, a practical example, and what to include in your cash budget.
QUESTIONS ARE A GOOD PLACE TO START
Common mortgage questions.
Do I need 20% down?
Not always. Fannie Mae’s HomeReady program offers down payments as low as 3% for eligible borrowers. Income, property, underwriting, and other restrictions apply. A smaller down payment may require mortgage insurance.
Read the full answer and example →
Explore Fannie Mae Selling Guide ↗Wondering how this applies to you? Ask Enrique →
How is my mortgage eligibility determined?
A lender reviews your credit, income, debts, assets, occupancy, and the property. Automated underwriting findings and the lender’s own requirements also matter. A calculator or chat answer cannot determine approval.
Read the full answer and example →
Explore Fannie Mae Selling Guide ↗Wondering how this applies to you? Ask Enrique →
What does debt-to-income mean?
Debt-to-income compares qualifying monthly debt payments with qualifying gross monthly income. Which payments and income count depends on the program and underwriting method. Ask a loan officer to review your complete scenario.
Read the full answer and example →
Explore Freddie Mac Seller/Servicer Guide ↗Wondering how this applies to you? Ask Enrique →
Can I use gift funds?
Under Fannie Mae B3-4.3-04, eligible personal gifts may cover funds for an eligible one-unit principal-residence transaction without a minimum contribution from the borrower’s own funds. The donor must be acceptable, a signed gift letter must state that repayment is not expected, and the lender must verify the source and transfer. Different property and program rules can change this.
Read the full answer and example →
Explore Fannie Mae · B3-4.3-04 · Personal Gifts ↗Wondering how this applies to you? Ask Enrique →
Can I get a mortgage if I’m self-employed?
Self-employed borrowers may qualify. The lender evaluates documented income, business history, stability, and applicable tax returns or other permitted documentation. Business revenue is not the same as qualifying personal income.
Read the full answer and example →
Explore Fannie Mae Selling Guide ↗Wondering how this applies to you? Ask Enrique →
Can rental income help me qualify?
Potential rental income may be usable when the program’s property, history, documentation, and calculation requirements are met. The lender must also account for applicable housing expenses and liabilities.
Read the full answer and example →
Explore Freddie Mac Seller/Servicer Guide ↗Wondering how this applies to you? Ask Enrique →
How are FHA loans different?
FHA insures eligible loans made by approved lenders. Handbook 4000.1 sets FHA policy for origination, underwriting, and other loan requirements. Eligibility, mortgage insurance, and property standards need individual review.
Read the full answer and example →
Explore HUD / FHA Handbook 4000.1 ↗Wondering how this applies to you? Ask Enrique →
Does FHA require an appraisal?
FHA appraisal and property requirements are covered in Handbook 4000.1. An appraisal serves a different purpose from an independent home inspection; discuss both with your lender and real estate professional.
Read the full answer and example →
Explore HUD / FHA Handbook 4000.1 ↗Wondering how this applies to you? Ask Enrique →
Should I refinance for a lower rate?
Compare the new payment, closing costs, remaining term, loan balance, and how long you expect to keep the loan. A lower payment alone does not establish savings. A loan officer can compare the full costs of your options.
Read the full answer and example →
Explore Fannie Mae Selling Guide ↗Wondering how this applies to you? Ask Enrique →
Can I take cash out of my home?
Fannie Mae B2-1.3-03 includes separate ownership and mortgage-age requirements: generally at least one borrower must have been on title for six months, and an existing first mortgage being paid off must be at least 12 months old. Exceptions apply. The maximum financing ratio also depends on the applicable eligibility matrix, property, and underwriting. Have your loan officer check the complete rule for your situation.
Read the full answer and example →
Explore Fannie Mae · B2-1.3-03 · Cash-Out Refinance ↗Wondering how this applies to you? Ask Enrique →
Are interest rate and APR the same?
The interest rate is used to calculate interest on your balance. APR also reflects certain financing charges. Compare written disclosures with consistent loan amounts, terms, and assumptions; the payment planner here does not calculate APR.
Read the full answer and example →
Explore Fannie Mae Selling Guide ↗Wondering how this applies to you? Ask Enrique →
What are points and lender credits?
Points are upfront loan charges expressed as a percentage of the loan amount. Lender credits may offset closing costs, often in exchange for a different interest rate. Request a written side-by-side comparison of rate and total costs.
Read the full answer and example →
Explore Fannie Mae Selling Guide ↗Wondering how this applies to you? Ask Enrique →
Is an online quote a rate lock?
No. A rate is not locked until the lender confirms the lock and its terms. Pricing depends on the full scenario, lender adjustments, lock period, and availability. Request written confirmation before relying on a rate.
Read the full answer and example →
Explore Fannie Mae Selling Guide ↗Wondering how this applies to you? Ask Enrique →
Why might a lender require more than the agency guide?
Lenders may impose additional requirements, often called overlays. Agency eligibility alone does not ensure a particular lender will approve or purchase a loan. Have the lender confirm the applicable rules for your scenario.
Read the full answer and example →
Explore Freddie Mac Seller/Servicer Guide ↗Wondering how this applies to you? Ask Enrique →
Can I finance a condo or second home?
Property type and occupancy change the review. Condos may require project eligibility review, and second homes or investment properties have different conditions from primary residences. Share the exact property details with your lender.
Read the full answer and example →
Explore Freddie Mac Seller/Servicer Guide ↗Wondering how this applies to you? Ask Enrique →
Where do I find VA, USDA, jumbo, or DSCR rules?
These programs are not fully governed by the three guides in this knowledge center. VA and USDA have their own official guidance; jumbo and DSCR requirements depend on the lender. Ask for a program-specific review.
Read the full answer and example →
Explore HUD / FHA Handbook 4000.1 ↗Wondering how this applies to you? Ask Enrique →
Is there one FHA debt-to-income limit for everyone?
FHA documentation distinguishes between automated underwriting using the TOTAL Mortgage Scorecard and manual underwriting. A single percentage quoted online is not an approval promise. Ask your loan officer to identify the underwriting method, applicable Handbook 4000.1 requirements, and any lender requirements before relying on a maximum.
Read the full answer and example →
Explore HUD · Handbook 4000.1 ↗Wondering how this applies to you? Ask Enrique →
How do I upload my underwriting documents?
Choose “Start your application” to open Enrique’s application portal. Complete your application there and follow the document tasks assigned in Arive. Upload underwriting documents directly in Arive; Enrique can clarify which records are needed. This website does not transfer application data or uploaded documents into Arive.
Read the full answer and example →
Explore Enrique’s Arive application portal ↗Wondering how this applies to you? Ask Enrique →
Can I compare cash-out debt consolidation?
Use the equity planner to enter your mortgage payoff, debt balances, current payments, cash needed, and an illustrative new rate and term. Compare the new payment and loan balance. A lower payment alone does not establish lifetime savings, and converting unsecured debt to home-secured debt changes the risk.
Read the full answer and example →
Explore Cash-out & debt planner ↗Wondering how this applies to you? Ask Enrique →
What is the 2026 loan limit in King or Snohomish County?
FHFA’s 2026 county list shows a one-unit conforming loan limit of $1,063,750 in King, Snohomish, and Pierce counties. This is a loan-amount limit, not a purchase-price limit or approval. Confirm the property county, unit count, program, and applicable year.
Read the full answer and example →
Explore FHFA · 2026 county loan-limit list ↗Wondering how this applies to you? Ask Enrique →
Where can I explore Washington down-payment assistance?
Start with Washington State Housing Finance Commission resources, then confirm current program availability with a participating lender. Ask about income eligibility, homebuyer education, repayment, and what happens when you sell or refinance. Assistance is not always a grant.
Read the full answer and example →
Explore WSHFC · Down-payment assistance ↗Wondering how this applies to you? Ask Enrique →
Photography and image credits
Lifestyle images are illustrative and do not depict Mortgage Lending Group clients or employees. Client reviews are separately attributed to their actual sources.
Seattle skyline: Josh Hild / Unsplash. Wallingford home (2006): brewbooks, CC BY-SA 2.0. Green Lake path (2017): Monikasj, CC BY-SA 4.0. Local photographs show these places when photographed, not current listings or MLG clients. Images resized, converted to WebP and cropped for display; adapted CC images retain their respective licenses.

