BUSINESS OWNERS · INDEPENDENT CONTRACTORS · PURCHASE & REFINANCE
Self-employed mortgage options in Seattle
You built a business. Your mortgage conversation should make room for how that business actually works. Start with your goal, your income documentation and a payment that leaves room for the rest of your life.
YOUR GOAL. A CLEAR NEXT STEP.
Your business is more than one number on a tax return.
Tell us how you earn, how long you have been in business and what you want your housing payment to feel like. We can review the documentation path before you spend time pursuing the wrong loan.
Describe your income and ownership structure.
Compare eligible documentation and financing paths.
Build a purchase or refinance plan around the verified numbers.
Start with your goal. Keep account numbers and financial documents out of a public question; we will direct you to a secure document process.
MORE THAN TWO DECADES OF EXPERIENCE
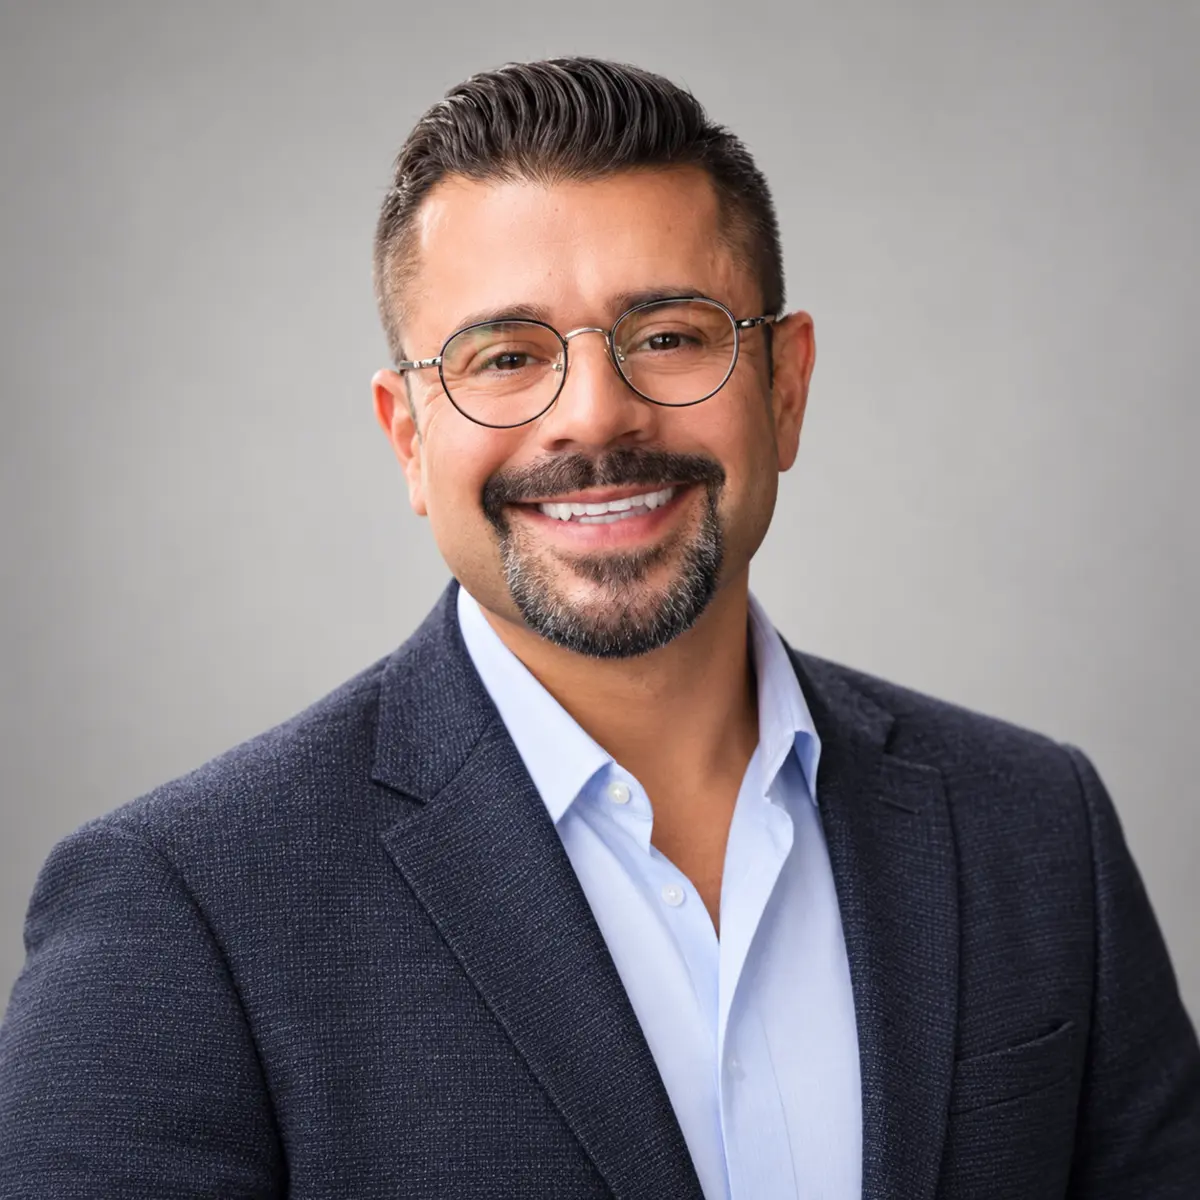
Enrique Pelayo Jr, AMPFounder of Mortgage Lending Group LLC. Personal guidance for home purchases, refinancing and equity decisions, in English and Spanish. Serving Seattle and nearby communities from Edmonds.
NMLS #131435 · Mortgage Lending Group LLC · CL-1157983
What does the AMP designation mean?
AMP stands for Accredited Mortgage Professional. The Mortgage Bankers Association awards this designation to graduates of its three-course School of Mortgage Banking. It represents additional professional education in the mortgage business.
That education complements Enrique’s hands-on experience explaining costs, choices and the mortgage process. The designation is separate from a state license and does not guarantee approval or a particular rate.
View Enrique’s AMP credential ↗ · MBA program requirements ↗Compare the documentation path before choosing the loan.
First, ask whether a conventional loan can fit your documented circumstances. Fannie Mae’s guidance calls for analysis of income stability and the business’s ability to keep generating income. It generally uses a two-year earnings history, with exceptions and specific documentation rules. One tax-return number is not a complete underwriting decision. Read Fannie Mae’s self-employed borrower guidance.
Some lenders offer bank statement programs that assess eligible deposits and may apply business expense factors. Angel Oak’s published program is one example of that approach, not confirmation of an offer through MLG or your eligibility. Ask which program is actually available, what documentation it requires and how its full cost compares.
| Your situation | What to compare |
|---|---|
| Established business with tax returns | Whether a conventional review fits before considering alternatives |
| Deposits tell a different story from taxable income | Eligible deposits, business expenses, ownership and alternative-program costs |
| Using business cash at closing | Required documentation and the effect of the withdrawal on business operations |
| Buying a rental rather than your own home | Personal-income financing versus a potential property-income approach |
What should you bring to the first conversation?
You can start without sending documents. Explain your work, ownership share, years in business, whether income has changed and your purchase or refinance timeline. When a document review is appropriate, use the secure application process Enrique provides.
- Your target payment, expected down payment and cash you want to retain.
- A summary of available tax returns, business records and account statements.
- The property address, if known, and whether it will be your home or a rental.
- Any existing mortgage quote and questions about the income calculation.
Keep business operating cash separate from your household comfort zone. If you plan to use business assets at closing, Fannie Mae’s guidance can require a cash-flow review to assess the impact on the business. Confirm the requirements before moving funds.
Make the Seattle property fit the plan, too.
A condo payment includes more than the mortgage. Association dues and potential assessments belong in your budget. For a house, leave room for insurance, taxes and repairs. If you are comparing Seattle with a home in Snohomish or Pierce County, use property-specific estimates rather than assuming the same costs.
For a clearly hypothetical household with $80,000 available and a personal goal of retaining $25,000, only $55,000 remains for the down payment and other closing cash. That is a planning illustration—not a lender reserve rule, required down payment or current market price. Keep business reserves outside this example.
Build a purchase scenario · Check county loan limits · Compare rental-property financing questions
A few questions before you start
Can I qualify for a mortgage if I am self-employed?
Potentially. Self-employment does not by itself prevent a mortgage. The lender must evaluate documented income, debts, credit, assets and the property. Start with the documentation you have and a realistic payment goal.
Do I automatically need a bank statement loan?
No. First compare whether a conventional documentation path fits. A bank statement program may be an alternative for an eligible borrower, but it has its own costs and requirements. Availability must be confirmed for your transaction.
Does every deposit count as mortgage income?
No. Ask the lender which deposits are eligible, how business expenses and ownership are treated, and which documents support the calculation. Gross deposits are not the same as spendable personal income.
Can I use money from my business for a down payment?
That requires a review. Business funds used for the transaction may need additional documentation and an analysis of the effect on the business. Do not transfer money solely on the assumption it will qualify.
Where is Mortgage Lending Group based?
Mortgage Lending Group LLC serves Seattle-area borrowers from 123 2nd Ave S, Suite 230, Edmonds, WA 98020. Enrique Pelayo Jr, AMP, NMLS #131435, offers guidance in English and Spanish.
Let’s figure out your next useful step.
Tell Enrique what you want to accomplish. We can identify the documentation questions, compare potential paths and explain what needs to happen before a lender can make a decision.
Ask Enrique about my situationMeet Enrique and verify his credentials · Orientación en español · Considering a refinance?