Spokane COUNTY · WASHINGTON
Mortgage Broker in Spokane Valley, WA
Considering a Spokane Valley property with an accessory dwelling unit? Verify the city permit record and the unit’s actual status before relying on it in your housing or financing plan.
Mortgage Lending Group LLC serves Spokane Valley from 123 2nd Ave S, Suite 230, Edmonds, WA 98020. Enrique Pelayo Jr, AMP · NMLS #131435 · English & Spanish.
Educational guidance · Updated 2026-09-26 · Our content standards
MORE THAN TWO DECADES OF EXPERIENCE
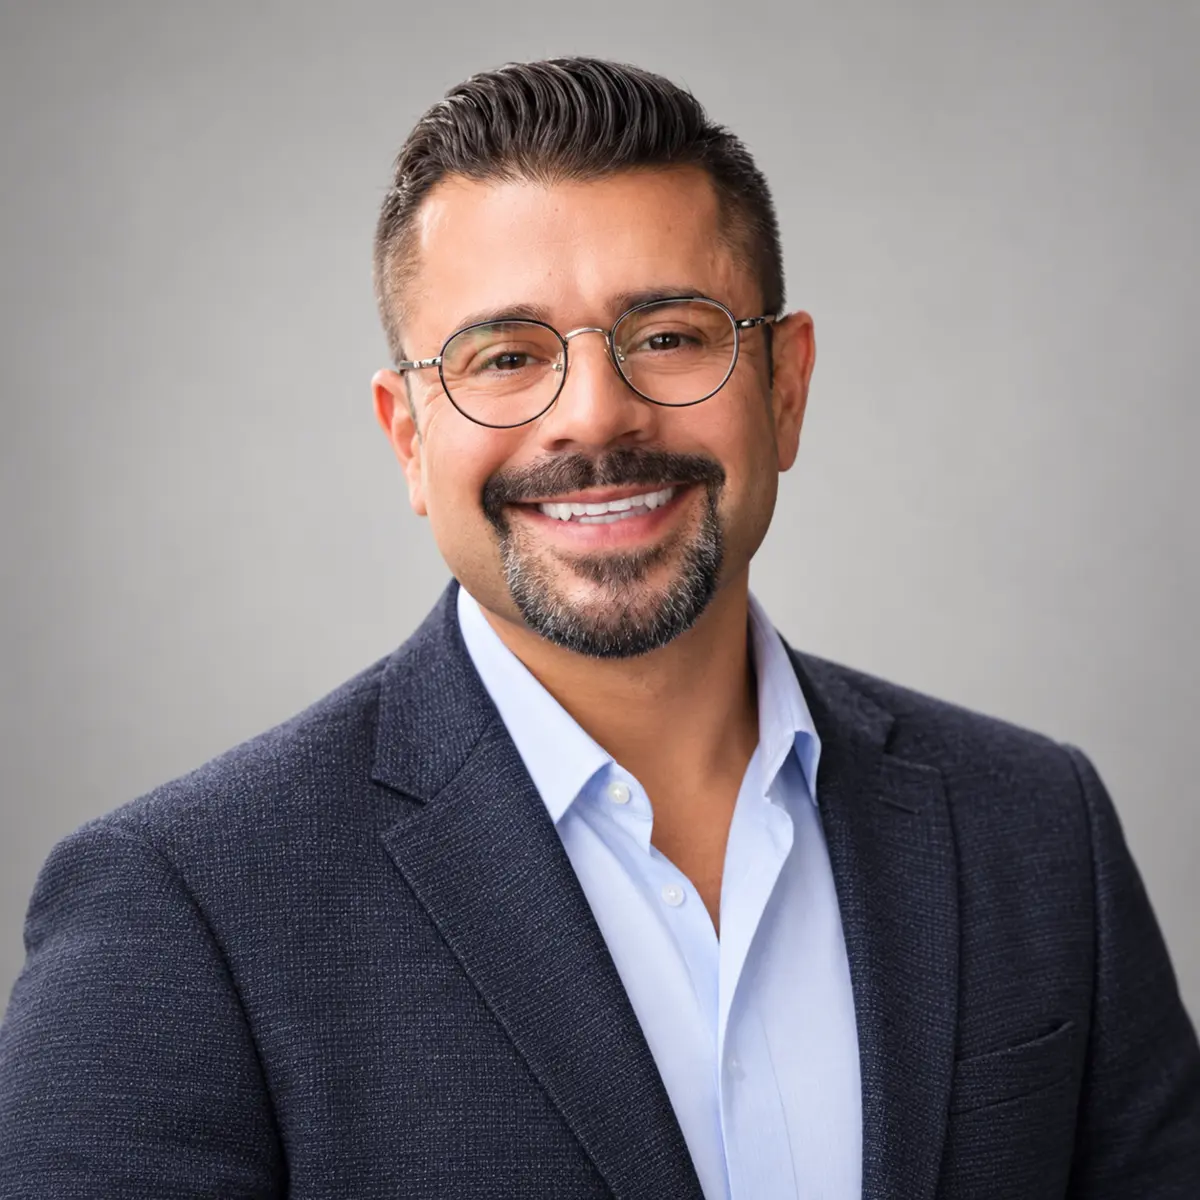
Enrique Pelayo Jr, AMPFounder of Mortgage Lending Group LLC. Personal guidance for home purchases, refinancing and equity decisions, in English and Spanish. Serving Seattle and nearby communities from Edmonds.
NMLS #131435 · Mortgage Lending Group LLC · CL-1157983
What does the AMP designation mean?
AMP stands for Accredited Mortgage Professional. The Mortgage Bankers Association awards this designation to graduates of its three-course School of Mortgage Banking. It represents additional professional education in the mortgage business.
That education complements Enrique’s hands-on experience explaining costs, choices and the mortgage process. The designation is separate from a state license and does not guarantee approval or a particular rate.
View Enrique’s AMP credential ↗ · MBA program requirements ↗BEFORE YOU CHOOSE A LOAN
Check what is included in the property
For a Spokane Valley home with extra structures or unusual land features, share the listing and intended use with your lender early. Verify permits, utilities and whether any business use changes the financing conversation. Do not assume a workshop or additional dwelling contributes its construction cost dollar-for-dollar to appraised value.
Will an outbuilding increase my borrowing power?
Its value and eligibility depend on the property and appraisal, not simply its size or construction cost. Get a property-specific review before counting on it.
Verify a Spokane Valley ADU before counting on its use
Spokane Valley’s Permit Center defines an accessory dwelling unit as an attached or detached independent living space on the same property and directs residents to the municipal-code requirements, application materials, permit search and fee resources. A listing description alone does not establish that an additional living area was approved as an ADU.
Before you commit: Search the city permit record for the exact address, compare the approved use with the space you toured, and ask the Permit Center about unresolved questions. Have the lender separately review the property and any proposed rental income; a permit record does not determine loan eligibility or appraised value.
City of Spokane Valley: accessory dwelling units ↗Source checked 2026-09-20 · Source publication date not provided. This is planning guidance, not a new-policy announcement.
Keep a Spokane Valley repair plan separate from loan approval
For a Spokane Valley home, turn inspection questions into a cash plan before choosing your down payment. Obtain estimates for immediate work and keep them separate from long-term upgrades you may postpone. A loan approval does not establish that a house has no repair needs or that a particular improvement will add value.
Use the official local resource linked here to investigate property and project requirements. If an addition, converted space or accessory dwelling affects your plans, ask about documentation and permitted use. Lender property review, insurance underwriting and local approval are separate checks.
An illustrative $450,000 purchase with 10% down uses $45,000 toward the price and leaves a $405,000 base mortgage. Build an additional line for closing costs, taxes, insurance and a repair reserve. Compare a smaller down payment with its mortgage-insurance cost before deciding how much cash to retain.
Spokane County’s 2026 one-unit conforming limit is $832,750. Verify the property county, number of units and financing program before applying that figure. If you already own, compare keeping the first mortgage with a refinance or separate equity loan using the same cash need and payoff horizon.
Compare mortgage rates and assistance in Spokane Valley
Use the same property details, down payment and lock period when comparing Seattle and Washington mortgage rates. Include taxes, insurance, mortgage insurance and any association dues in your budget.
Considering help with closing cash? Read the WSHFC Home Advantage guide and ask a Commission-trained lender to confirm eligibility and participation. Assistance is a separate obligation; compare the repayment terms alongside the first mortgage.
MAKE IT YOURS
Does the monthly cost fit your life?
Put an actual Spokane Valley property alongside your comfort limit. Use a lender estimate for principal, interest and mortgage insurance; add the costs it may leave out.
Fill in all six amounts to see the comparison. Enter 0 only for costs that do not apply.
Planning only. This does not calculate a mortgage payment or determine approval. Estimates can change. These inputs stay in this page and are not submitted or saved.
ALREADY OWN IN SPOKANE VALLEY?
Your next move might be staying put.
For a planned addition, compare financing options only after checking permits, a realistic budget and the need for contingency funds.
The sample uses fictional numbers. A home-value estimate is not an appraisal, and equity is not automatically available to borrow.
Check the details at the source.
- Spokane Valley city services and property resources ↗ — starting point for city services and property questions; a mailing address does not establish jurisdiction.
- CFPB: compare loan offers ↗ — compare the full terms and costs.
- Washington Commerce: homeownership resources ↗ — independent assistance and counseling resources.
These resources are independent of Mortgage Lending Group LLC. They do not endorse this guide. Availability, eligibility and property rules require current confirmation.
Explore more of Eastern Washington.
Seattle mortgage broker: loan limits, buyer programs and payment planning →
This is a service-area guide, not a branch-office listing. Mortgage services are provided through Mortgage Lending Group LLC. Educational planning is not a rate quote, commitment, approval or individualized tax or legal advice. Rates, costs, eligibility and values vary. Professional background and licensing.